Pilot training installment payment plans India case study: A practical guide
A milestone-based installment plan let one Delhi family fund their son's commercial pilot training in four staged payments. Each payment was released only after a training checkpoint was verified on a digital dashboard. This pilot training installment payment plans India case study shows how the stages, triggers, and bank moratorium fit together. Other parents can copy this structure.
Key Takeaways
- Four payment stages, not one lump sum: Ground school, simulator, flight training and type rating were billed separately. Each was tied to a verified milestone, not a calendar date.
- Dashboard data justified every release: The parent used subject-wise mock scores and logged simulator hours on the RAPT dashboard before he approved the next installment.
- Education loan covered two of the four stages: A public sector bank loan, backed by a co-applicant and collateral, funded the flight training and type rating stages.
- The moratorium period mattered most: Loan repayment only started 6 months after training finished. By then, the son had a first officer role and could pay from his own salary.
- Simulator scheduling caused the one real friction point: A delay in simulator slot availability pushed the second payment back three weeks. It's a genuine trade-off of milestone billing worth knowing before you sign up.
At a Glance: This Case Study's Payment Structure
| Stage | Approx. Share of Total Cost | Disbursement Trigger | Funding Source |
|---|---|---|---|
| DGCA Ground School | 15% | Enrollment + first month attendance verified | Family savings |
| Fixed-Base Simulator Training | 20% | Ground school subject scores cross 70% average | Family savings |
| CPL Flight Training | 45% | Simulator hours logged and instructor sign-off | Education loan (disbursed in tranches) |
| Type Rating Preparation | 20% | CPL license issued, hours logged in digital logbook | Education loan |
| Loan Repayment Start | — | 6 months after course completion | Son's own salary post-placement |
The Family Behind This Pilot Training Installment Payment Plans India Case Study
The family runs a small trading business in Delhi. Their son finished 12th grade with Physics, Chemistry and Maths, and wanted a commercial pilot license. They read about hidden fees that catch parents off guard. A single upfront payment felt too risky.
The father worked in retail cash flow, not on a fixed salary. Paying the full course fee in one transfer meant breaking a fixed deposit meant for his daughter's wedding fund. That risk pushed him to ask the academy about a staged plan instead.
Rian Air's admissions team proposed splitting the total fee into four stages. These stages mirrored the real training sequence: ground school, simulator, flight training, and type rating preparation. Each stage had a clear entry condition, not just a date on a calendar.
Why a Lump-Sum Fee Structure Did Not Work for This Family
Paying everything upfront means trusting an 18-month outcome before day one is done. If a student fails ground school theory, a lump-sum payer has already funded flight training slots they may never use.
The family also worried about the reverse problem: paying for a service before it happens, with no way to check progress except a phone call to the front desk. That is the exact gap a parent dashboard for tracking pilot training progress is built to close.
How the Milestone-Based Installment Plan Was Structured
The academy and family agreed on four payment stages. Each was tied to a training milestone, not a fixed month. This matters because flight training delays due to aircraft availability are common. Calendar-based billing punishes students for delays outside their control.
Ground school payment was released after enrollment and one month of verified attendance. The simulator stage required a 70% average across mock DGCA subject tests. This used the fixed-base simulator training readiness criteria instructors already track.
Flight training payment was staged in two parts inside the education loan itself. Each part was released as logged simulator hours crossed set thresholds. Type rating preparation was billed only after the CPL license was issued and hours were confirmed in the digital logbook.
How the RAPT Parent Dashboard Justified Each Disbursement
The RAPT dashboard justified each payment. It gave the father subject-wise mock scores, simulator hour logs, and instructor remarks in one login. This replaced guesswork with a clear record before he approved the next payment.
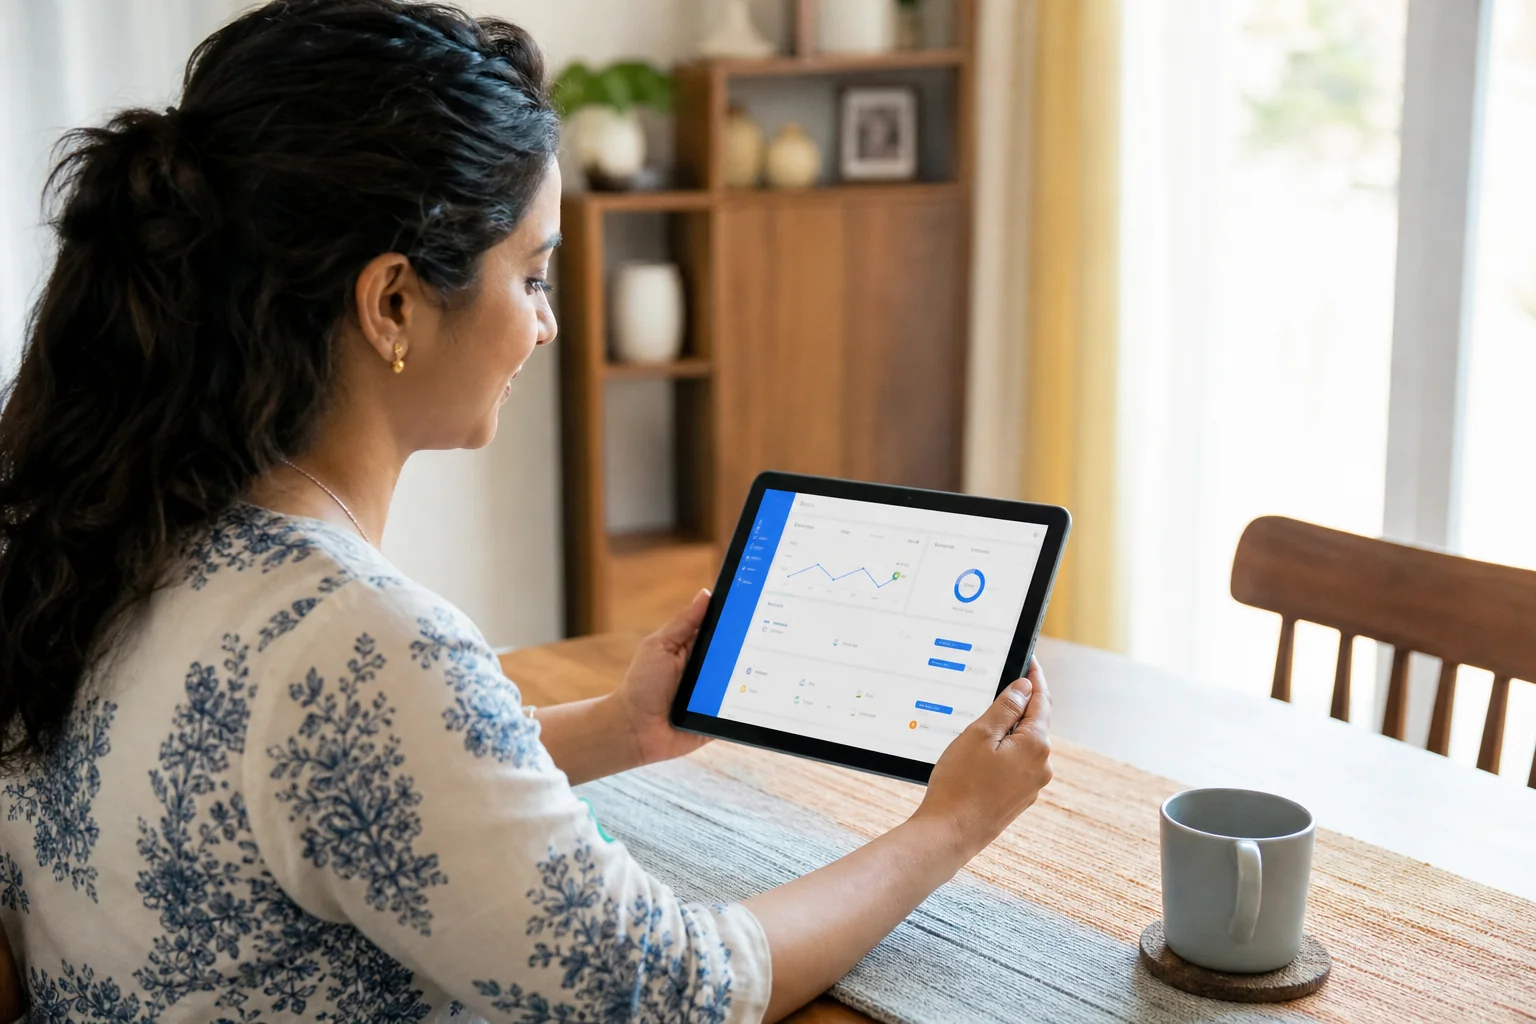
Before this case, the father's only proof of progress was a phone call. With the dashboard, he could see which DGCA subjects his son was weak in. He could check if simulator hours matched the syllabus pace. He could see if instructor notes flagged any concern. A green milestone status was his cue to release funds, not a reminder call from the accounts office.
This shifted the relationship from trust-based to evidence-based. Neither side had to argue about whether a stage was "basically done." The dashboard data either supported the release or it did not.
Where Does an Education Loan Fit Into an Installment Plan?
An education loan covers the two largest stages: flight training and type rating. These carry the highest per-hour cost and the longest duration. Approval depends on academic record, a co-applicant with steady income, and collateral above roughly ₹7.5 lakh.
The family's public sector bank required the father as co-applicant. Their family home served as collateral for the amount beyond the unsecured threshold. This lines up with the standard criteria in our education loan for pilot training eligibility guide. What made the difference here: the loan was released in tranches that matched the academy's own milestone stages. The bank never released funds faster than training progress justified.
Why the Moratorium Period Matters More Than Most Parents Realise
A moratorium period lets the bank delay loan repayment for 6 to 12 months after training completion. This gives the graduate time to land an airline or instructor job. He can then start repaying from his own salary, not his parents' funds.
In this case, the son's loan carried a 6-month moratorium starting from course completion. During that window, he was job-hunting, not earning a salary. By the time EMIs (equal monthly installments) began, he had already secured a first officer training role. He could pay the installment himself.
This detail changed the family's entire risk picture. Without a moratorium, the father would have needed to keep paying the loan out of his own trading income right through his son's job search. This was on top of the earlier payments already made from savings. With the moratorium, the repayment burden moved off his shoulders at just the right time.
Parents evaluating loans should ask each bank directly for the moratorium length. Ask too whether interest still builds up during that window. Some banks add interest into the principal even while repayment is paused.
Cheap Pilot Training: What an Installment Plan Can and Cannot Fix
An installment plan reduces the immediate cash burden of pilot training. It does not lower the total cost. Families searching for cheap pilot training often mistake a low headline fee for real affordability. The real comparison is total lifetime cost spread over a realistic payment schedule.
A milestone-based plan protects against paying for training stages that never happen. It does not protect against an academy quoting a low base fee, then adding simulator, checkride, or type rating charges later. This pattern is explained in why cheapest flight training does not exist. Ask any academy offering installments for a complete, stage-by-stage fee schedule before you sign anything. Don't settle for just the ground school number.
Comparing Payment Approaches for Pilot Training in India
| Approach | Upfront Burden | Visibility Into Progress | Best Suited For |
|---|---|---|---|
| Full Lump-Sum Payment | Very high, entire fee at admission | Low, no built-in verification checkpoints | Families with liquid savings and low risk tolerance for delays |
| Milestone-Based Installments | Low per stage, spread across 18-24 months | High, if paired with a dashboard | Families wanting cash-flow control and progress checks |
| Education Loan (No Moratorium) | Moderate, EMIs start immediately | Depends on bank reporting, usually low | Families comfortable repaying while the student is still training |
| Education Loan With Moratorium | Low during training, resumes post-placement | Depends on bank reporting, usually low | Families wanting the graduate to repay from their own salary |
What Went Right in This Case, and What Would We Change
The dashboard-linked milestone plan removed the biggest source of parent anxiety: not knowing whether money was buying real progress. Payments were tied to a subject-wise score threshold, not a date. This meant the family never paid ahead of actual training delivery.
The one genuine friction point was scheduling. Simulator slot availability pushed the second payment back roughly three weeks compared to the original plan. The academic milestone (a 70% average across mocks) was reached before the simulator hours needed for the next stage. No dashboard fully solves this gap; it's a scheduling constraint that milestone billing exposes rather than causes. Families should expect some slippage. Build a small buffer into your own cash planning rather than assume payment dates are fixed.
How Parents in Delhi, Maharashtra and Kerala Can Set Up a Similar Plan
Start by asking any shortlisted academy for a written, stage-wise fee breakdown before enrollment. Then confirm whether progress data, like scores, simulator hours, and instructor notes, will be shared through a dashboard rather than by phone.
Families in Delhi, Maharashtra, or Kerala evaluating this route should:
- Request the total fee split by training stage, not just a headline course fee.
- Ask which milestones trigger each installment, and whether those milestones are visible on a live dashboard.
- Check if the academy accepts partial funding through an education loan alongside family savings, and whether disbursement tranches can be aligned with loan tranches.
- Ask each shortlisted bank directly about moratorium length and whether interest builds up during that period.
- Build in a scheduling buffer of at least three to four weeks per stage. Simulator and aircraft availability can shift payment timing even when academic milestones are met on time.
According to the Directorate General of Civil Aviation, CPL training in India follows a fixed regulatory sequence: ground exams, simulator hours, then flight hours. This is exactly why milestone billing maps so cleanly onto training progress here. Banks listed under the Ministry of Education's education loan schemes also structure payments in tranches for similar reasons. This reduces risk for both the lender and the family.
Parents comparing international pathways alongside financing should also read our breakdown of CPL training in India vs Malta vs Tunisia. Currency exposure changes how a milestone plan should be structured for training abroad.
One thing this case study leaves unresolved: should a fixed penalty clause for academy-side scheduling delays be a standard part of installment agreements? This family absorbed the three-week slip without dispute. A future family might reasonably ask for that protection written in upfront.
If your family is weighing a lump-sum payment against a staged plan, start your enquiry with Rian Air's admissions team to get a stage-wise fee breakdown built around your own cash flow. You can also explore pathways across ground school, simulator, flight training and type rating before committing to any payment structure. For real training footage and student updates, follow along on Instagram or subscribe on YouTube.